
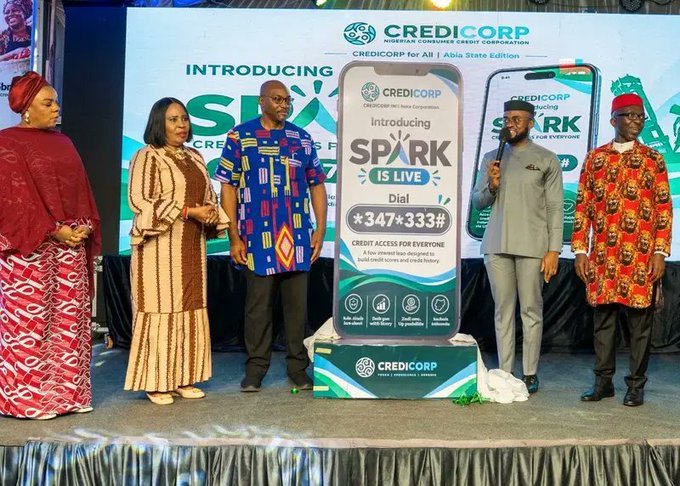
The Federal Government has launched SPARK, a new USSD-based credit service designed to help Nigerians access loans and build formal credit histories using basic mobile phones. The platform allows users to access financial services by dialing *347*333#, eliminating the need for smartphones, mobile apps, or internet connectivity.
The initiative addresses one of the biggest challenges in Nigeria’s financial system: access to credit. While millions of Nigerians own mobile phones, a significant number remain excluded from formal lending because they lack a banking history, collateral, or access to digital financial platforms. SPARK seeks to bridge that gap by creating a pathway for underserved individuals to establish verifiable credit records.
The launch comes at a time when financial inclusion has become a major priority across Africa. Governments, banks, and fintech companies are increasingly exploring ways to bring more people into the formal financial system. For small business owners, traders, artisans, farmers, and low-income earners, access to credit can mean the difference between maintaining a livelihood and growing a business.
What makes SPARK particularly significant is its accessibility. By relying on USSD technology rather than internet-based applications, the platform reaches people in communities where smartphone ownership, data access, or internet connectivity remain limited. This approach reflects a practical understanding of Nigeria’s diverse digital landscape.
The service could also contribute to the development of a stronger credit culture in Nigeria. Many individuals struggle to secure loans because they lack documented borrowing histories. By helping users build formal credit profiles over time, SPARK has the potential to unlock broader financial opportunities, including access to banking products and enterprise funding.
As Nigeria continues its push toward a more inclusive digital economy, initiatives like SPARK demonstrate how technology can be adapted to local realities. The success of the platform will ultimately depend on adoption, transparency, and how effectively it expands access to responsible lending for millions who have traditionally remained outside the formal credit system.